Marriage is supposed to be a partnership of shared goals, mutual trust, and a unified vision for the future. For six years, Mark and I had exactly that. We saved for a down payment, picked out a fixer-upper in the suburbs, and meticulously managed our finances to ensure we were never drowning in debt. We were the couple our friends envied for our stability. I trusted him implicitly with our joint accounts, never bothering to check the balance of his paycheck deposits because we had a system that worked.
That trust was shattered on a Tuesday afternoon when a thick envelope arrived from the bank. It wasn’t a standard statement; it was a ‘Notice of Intent to Foreclose.’ My stomach dropped as I tore it open, my hands trembling. Two months of mortgage payments hadn’t been made. I immediately assumed it was a bank error, a glitch in the system, or perhaps a delay in the automatic transfer. But when I logged into our online portal, the reality was far more devastating than a technical error.
The account was bone-dry. Not only had he missed the mortgage payments, but he had systematically drained our emergency savings and our vacation fund. My heartbeat quickened as I scrolled through the transaction history. The culprit wasn’t an emergency medical bill or a secret debt collector. It was a recurring monthly withdrawal labeled under a luxury vehicle dealership that I had never heard of. My husband had prioritized a shiny, ego-driven machine over the roof over our heads.
I didn’t scream when he walked through the door that evening. I didn’t throw plates or demand an explanation. I sat in the living room with the papers spread out on the coffee table, watching him pull into the driveway. He wasn’t driving our sensible sedan. He was driving a matte-black luxury coupe that looked like it cost more than my first year of law school. The sight of it felt like a slap to the face, a physical manifestation of his selfishness.
As he stepped out of the car, grinning at his new toy, he didn’t notice me watching him from the shadows of the foyer. He was on his phone, likely bragging to someone about the horsepower or the leather interior. In that moment, the love I felt for him didn’t vanish—it solidified into cold, hard logic. I realized that if I didn’t act immediately, I would be homeless because of his vanity. I didn’t need a divorce lawyer yet; I needed a strategy to save my future, and I knew exactly how to clip his wings.
The Reveal of the Shiny Deception
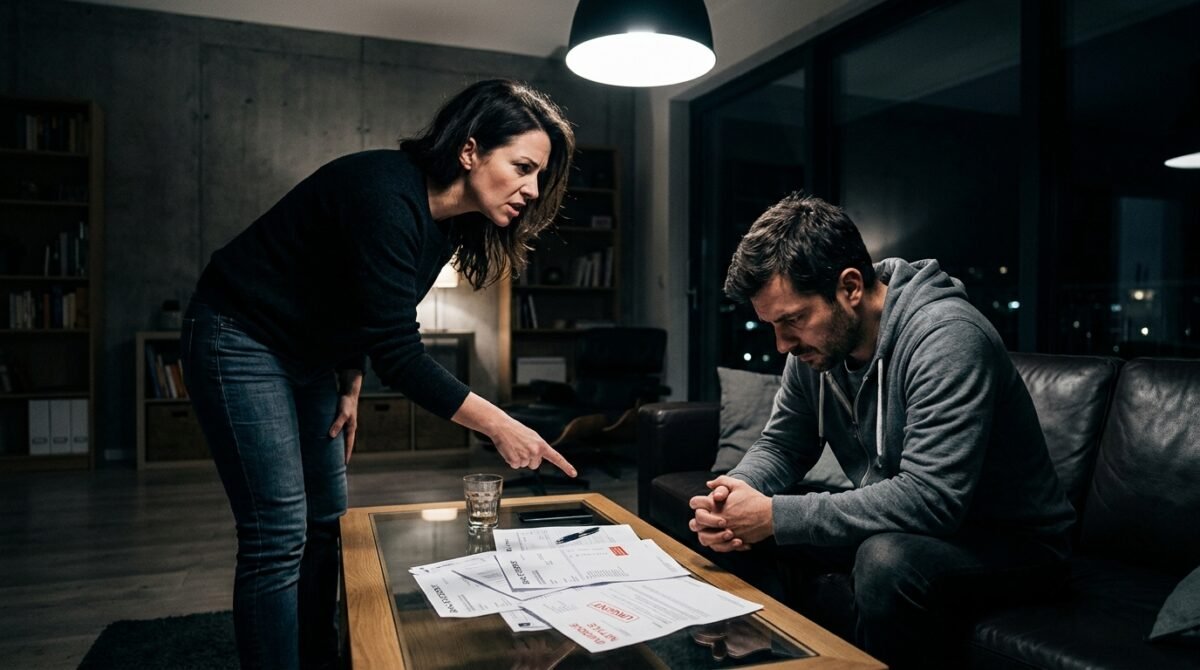
Mark walked into the house, his face still flushed with the adrenaline of his new purchase. He didn’t see the foreclosure notice on the table immediately. He walked past me, still talking on his phone, praising the ‘incredible handling’ of the car. I stood up, blocking his path to the kitchen. I didn’t say a word; I just pointed at the bank documents sitting next to his car keys.
He stopped mid-sentence. The grin faded, replaced by that familiar, sheepish look he used whenever he forgot to take out the trash or left his socks in the living room. But this wasn’t a minor chore oversight. This was a catastrophic failure of his responsibilities as a husband and a homeowner. He looked at the paperwork, then back at me, his eyes darting around as if searching for an exit.
“Mark, look at these dates. We are sixty days behind on the mortgage. Where is the money? I checked the savings. It’s gone. Tell me, right now, what is sitting in our driveway?”
He tried to deflect, stammering about ‘investment opportunities’ and ‘asset appreciation,’ which was clearly a load of nonsense he’d picked up from some online car forum. He told me the coupe was a ‘steal’ and that he’d ‘realign the budget’ next month. He completely minimized the gravity of missing two mortgage cycles. He treated our home as if it were a disposable asset, something that could be patched up with a quick payment later, while his new status symbol was non-negotiable.
I didn’t let him finish. I told him that the ‘realignment’ he was talking about meant we were currently on a path to eviction. He still looked at me as if I were overreacting, accusing me of being ‘too analytical’ about our finances. It was the moment I realized he didn’t just have a spending problem; he had a total disconnect from reality. He truly believed his ego was worth more than our security.
The Midnight Consultation
After he fell asleep—utterly unbothered, I might add—I spent the entire night researching. I wasn’t going to let him sink us. I reached out to a friend who practiced real estate law. I didn’t tell her everything, just enough to get the legal framework for what I needed to do. I learned about property liens and the specific ways a spouse can protect their interest in a marital home when the other party is acting with gross financial negligence.
By 4:00 AM, I had a plan. I wasn’t looking for a divorce at that exact second, but I was looking for leverage. I needed to ensure that no matter what happened, Mark couldn’t sell that house from under me, and he certainly couldn’t use our equity to pay off his mounting car payments. I realized that the bank was the immediate threat, but Mark was the systemic problem. If I didn’t stop him now, he would find another way to bleed us dry.
I drafted a formal document. It wasn’t just a threat; it was a preemptive strike. I spent hours studying our mortgage agreement, cross-referencing it with state laws regarding spousal financial abuse. The legal jargon was dense, but it was the most empowering thing I had ever read. I felt a surge of clarity. I wasn’t a victim anymore; I was a strategist protecting my own survival.
When the sun finally began to rise, I had a stack of documents ready to be notarized. I felt cold, calculated, and entirely justified. Mark’s entitlement had built this fire, and I was the one who had to build the barrier to keep it from consuming everything I worked for. I wasn’t doing this for spite, though a small part of me wanted him to feel the exact panic I felt when I opened that envelope.
The Morning Ambush
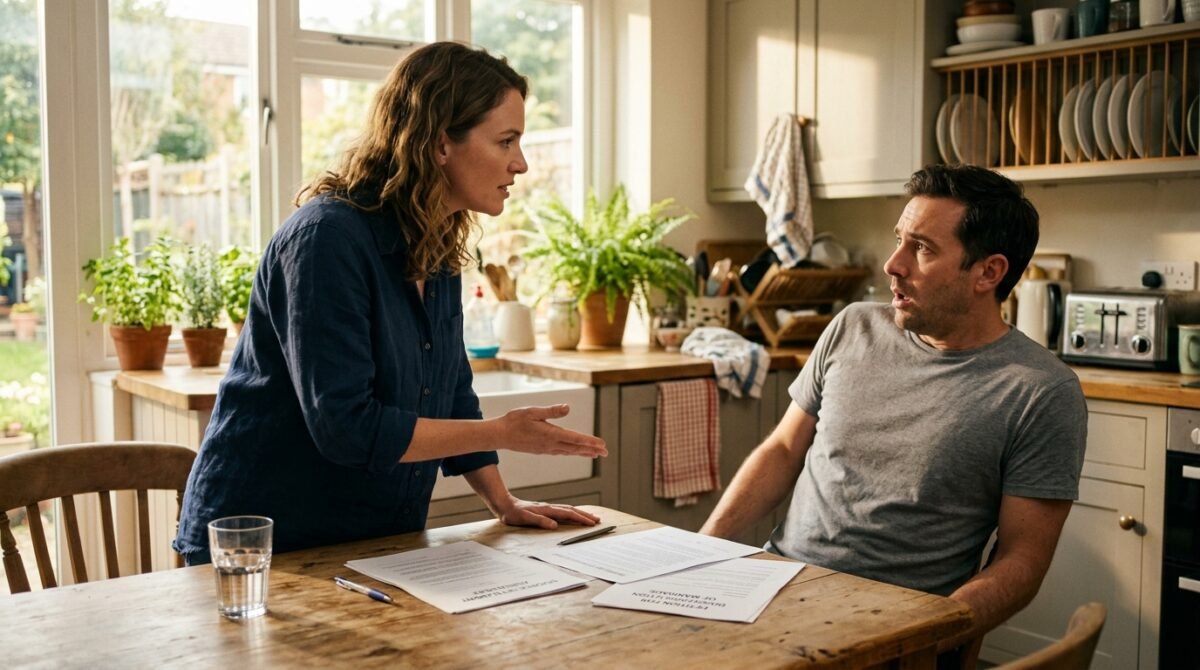
When Mark woke up, he was already looking at car accessories on his tablet. He had the audacity to ask me if I wanted to go for a ‘test drive’ to celebrate his new purchase. I looked at him, feeling a strange sense of pity. He was a grown man acting like a child who had just been given an allowance for the first time. I put the papers I’d prepared down on the table next to his breakfast.
“I’m not going for a ride, Mark. I’m going to the bank, and then I’m going to the county records office,” I said. His confusion was palpable. He started to laugh, thinking I was pulling some elaborate prank. Then he actually read the papers. His face went pale, and his hands started to shake. He finally understood that I wasn’t just complaining about a budget; I was taking control of the asset.
“A lien? You’re filing a lien on our house? This is our home! You’re going to ruin my credit for a stupid car you’re just overreacting about!”
He was furious. He stood up, knocking his chair back, and started shouting about how I was ‘betraying the partnership.’ I reminded him that the partnership died when he decided to prioritize a luxury coupe over our mortgage. I told him that the lien wasn’t to ruin his credit; it was to ensure that if the house was ever sold to cover the debts he created, I would be the first one compensated, and he would be forced to account for every cent he misappropriated.
The silence that followed was heavy. He realized I wasn’t bluffing. For the first time, he saw the depth of my resolve. He tried to grab my phone to call his parents, but I had already locked it. I told him he had until the end of the week to sell that car and pay back the mortgage, or I would be filing for a legal separation to protect the remaining assets.
The Group Chat Exposure
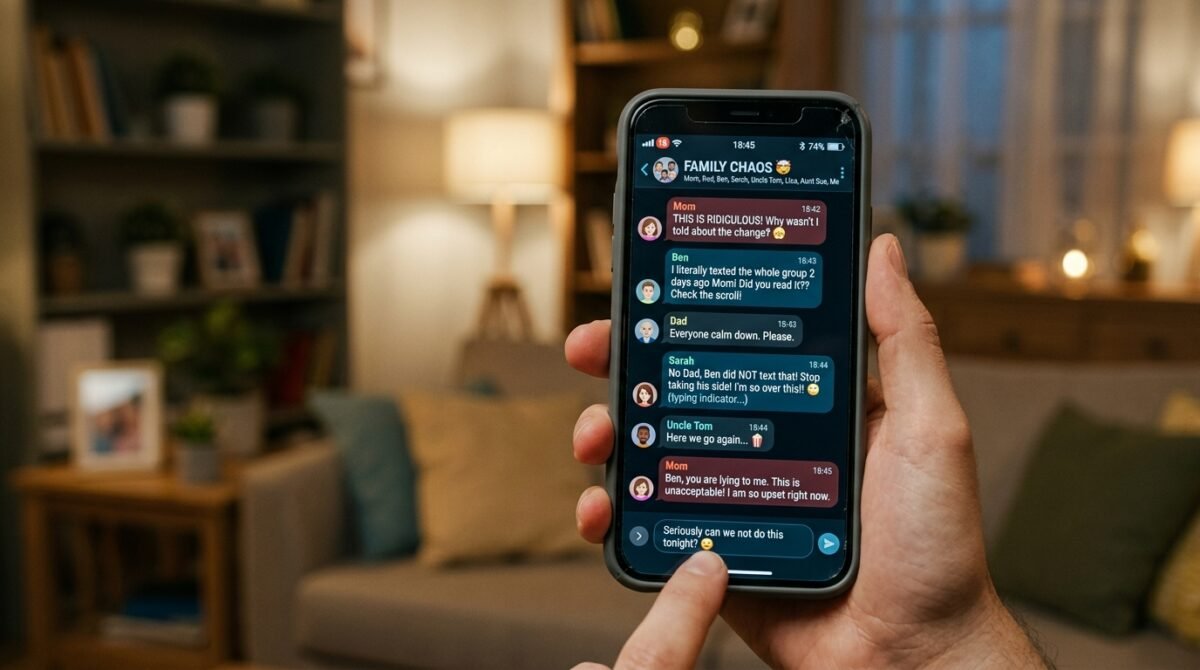
I knew Mark would try to spin the narrative to his family. He was the type of person who needed a fan club to validate his poor decisions. Sure enough, by noon, I started getting messages from his mother and his sister. They were confused, asking why I was being so ‘aggressive’ and ‘controlling’ over a ‘small financial mishap.’ It was clear Mark had painted me as the villain.
I didn’t engage in a shouting match. I took screenshots of our mortgage statements, the foreclosure notice, and the bank transfers to the luxury car dealership. I created a PDF document and sent it to the family group chat. I didn’t add any commentary; I just let the numbers speak for themselves. The response was immediate and deafeningly silent at the same time.
“Mark, did you really skip two months of mortgage payments to buy a car? Please tell me this is a lie.”
— Mark’s Mother, Family Group Chat
The messages started coming in thick and fast. His sister, who had always been the voice of reason, was appalled. She started grilling him, asking how he could be so reckless. Mark tried to argue that it was a ‘short-term investment,’ but his family wasn’t buying it. They realized that their ‘successful’ son was actually a financial train wreck who was about to lose his home.
I watched from my phone as the group chat turned into a roasting session. It wasn’t the petty drama I expected. It was a genuine intervention happening in real-time. Mark left the group chat within ten minutes, but the damage was done. He had lost his support system, and he had lost his ability to manipulate the narrative. I felt a cold sense of satisfaction watching his ego collapse in real-time.
The Dealership Showdown
The final straw was when I walked into the luxury dealership myself. I wasn’t there to make a scene; I was there to see if there was any way to undo the contract. I spoke to the manager and explained the situation. I told them that the vehicle was financed through funds that were meant for a mortgage, and I wanted to know if they had any ‘cooling-off’ period or if I could return the car to settle the debt.
The manager was professional but firm. He told me that once the paperwork was signed, the car was Mark’s. However, he did mention that the dealership had a ‘buy-back’ program, though it would come with a significant financial loss—about twenty percent of the original value. I told him that a twenty-percent loss was better than a foreclosure and a total loss of our home. I left my contact info and told him to have the paperwork ready if Mark decided to be reasonable.
When I got home, Mark was sitting on the floor of the garage, staring at the car. He looked defeated. He hadn’t expected me to go to the dealership. He had convinced himself that he could ‘figure it out’ by getting a side gig or selling some of his old collectibles. I told him that I had spoken to the manager and that we had a window to return the car, albeit at a loss.
“We can lose the car and keep the house, or we can lose the house and keep the car,” I said. He didn’t have an answer. He just cried. It wasn’t the cry of a man who was sorry; it was the cry of a man who realized his fantasy was over. I didn’t hug him. I didn’t offer comfort. I stood there, waiting for him to make the decision that would define the rest of our marriage.
The Reddit Trial
I posted my story on Reddit to see if I was truly the villain as Mark claimed. I didn’t expect the response I got. Within hours, the post hit the front page. Thousands of people commented, and the general consensus was clear: I wasn’t just in the right, I was arguably too lenient. The community validated everything I felt, providing me with resources and legal advice that I hadn’t even considered.
“Financial infidelity is just as damaging as any other kind of betrayal. You did the right thing by filing the lien. You protected yourself. Don’t let him guilt-trip you into thinking you’re the bad guy.”
— u/FinanceExpert42 (Top Comment, 32.1k upvotes)
There were hundreds of similar comments. People shared their own stories of being burned by partners who hid debts or made massive, reckless purchases. It made me realize that I wasn’t alone in this nightmare. The validation helped me stand my ground when Mark tried to negotiate later that evening. I wasn’t ‘crazy’—I was a victim of financial abuse.
Some users even pointed out that I should consult with a divorce attorney regardless of whether we sell the car. They suggested that Mark’s behavior was a symptom of something deeper, something that wouldn’t necessarily be fixed by selling a piece of metal. It was a hard truth to swallow, but it was one I needed to hear. The Reddit community acted as a mirror, showing me the reality of my situation without the bias of my emotional history with Mark.
The Financial Reckoning
We sold the car back to the dealership that weekend. The loss was painful, but it was the price of the lesson. We used the remaining funds to cover the missed mortgage payments and to pay the lawyer fees for the lien. The house was saved, but the trust was still in pieces. Mark had to take a second job to start rebuilding the savings he had drained.
Our financial life was now under a microscope. We closed all joint accounts and opened separate ones, with a third account for shared expenses that required both of our signatures for withdrawals over a certain amount. It was a tedious process, but it was necessary. Mark hated it. He felt like he was being treated like a child, but I reminded him that he had lost the privilege of being treated like a partner.
The tension in the house was palpable. We moved around each other like ghosts. There were no more shared dinners, no more casual conversations about our future. We were just two people living in a house we barely managed to save, waiting for the other shoe to drop. I started seeing a therapist to deal with the trauma of the betrayal, while Mark refused to see anyone, claiming he could ‘fix himself.’
I watched him struggle with his new reality. He had to take the bus to his second job, and he had to drive our old, beat-up sedan, which he now looked at with pure disdain. It was clear that he hadn’t learned the lesson of humility. He was just biding his time, waiting for the day he could prove he was ‘right’ all along. I knew then that the marriage was living on borrowed time.
The Breaking Point
The final end came not with a bang, but with a credit card statement. I found out he had opened a secret line of credit to buy a set of high-end rims for the old car, thinking I wouldn’t notice. It was such a pathetic, small act of defiance that it made me laugh. I didn’t even get angry. I just felt a profound sense of relief that I had already taken the steps to protect my assets.
I sat him down and served him the divorce papers. He was shocked, despite everything that had happened. He tried to argue that we were ‘getting better’ and that the rim purchase was a ‘one-time thing.’ I looked at him and realized I didn’t know the person sitting in front of me. He wasn’t the man I married; he was a stranger who happened to share my living space.
“This isn’t about the rims, Mark. It’s about the fact that you will never change. You will always choose yourself, and I am done being the collateral damage of your ego. We are over.”
He didn’t fight back. He knew he didn’t have a leg to stand on. The lien I had filed on the house ensured that he couldn’t walk away with half the equity without addressing the debt he had caused. It was the only thing that kept the divorce process from being a total disaster. I had protected my future, and now I could finally begin to build it without him.
Life After the Lien
Today, the house is officially mine. Mark moved out, and for the first time in years, the house feels like a home again. I’ve repainted the walls, changed the furniture, and reclaimed every single space that he had once tainted with his ego. I am still working on my credit score, and it will take a few more years to fully recover, but I am in control of my own destiny.
I see Mark occasionally in town. He’s driving a different car now, probably financed with another ridiculous loan. He looks older, tired, and still just as dissatisfied as he was when he had the luxury coupe. I don’t feel anger towards him anymore. I feel a strange sense of gratitude for the experience. It taught me exactly what I am capable of when my back is against the wall.
I started a blog where I write about financial independence and protecting yourself in marriage. It has become a community for others who have gone through similar betrayals. We share tips on legal protection, emotional healing, and how to spot the signs of financial abuse before it’s too late. It’s been the most rewarding thing I’ve ever done.
The lesson I learned is simple: trust is not a blind leap; it is a calculated decision based on consistency and honesty. When someone shows you who they are, believe them. And more importantly, never, ever let someone else be the sole guardian of your future. You are your own best advocate, and sometimes, that means making the hard, unpopular choices to keep your life from falling apart.
Reflections on the Financial Bond
Looking back, the most shocking thing wasn’t the car; it was the ease with which Mark thought he could discard our stability. He viewed our marriage as a playground for his impulses rather than a partnership. The lien wasn’t just a legal maneuver; it was a physical boundary that forced him to acknowledge that our home was not his personal bank account. It was the only way to make the invisible weight of his choices real.
The fallout from this experience changed my relationship with money forever. I no longer believe in ‘joint’ as a concept of total merger. I believe in ‘equitable’ and ‘transparent.’ I believe in having clear, written agreements even for the smallest household expenses. It might sound cynical to some, but it has saved me from the kind of anxiety that almost broke me. Peace of mind is far more valuable than a ‘joint’ bank account balance.
I hope that by sharing this, someone else might find the strength to stand their ground before they end up in the same position. You don’t have to wait for the foreclosure notice to take control of your financial life. You have the right to know where your money goes, and you have the right to protect the assets you’ve worked so hard for. Don’t be afraid to be the ‘difficult’ one if it means saving your life.
We need to stop normalizing financial abuse. We need to stop calling it ‘a mid-life crisis’ or ‘just a guy thing.’ It is a form of betrayal that strips away a person’s security and future. It is time we start treating financial infidelity with the same gravity as any other form of cheating, because at the end of the day, it is a theft of your trust and your potential.
Conclusion
The story of the luxury coupe and the mortgage lien is a stark reminder that we are all responsible for the foundations of our own lives. While marriage is a union, it is also a contract, and when that contract is violated, we must be prepared to defend our interests. My journey from a blind participant in a failing marriage to a guardian of my own future was painful, but it was necessary.
If you find yourself in a similar situation, remember that you are not powerless. You have options, you have legal rights, and you have a community that can support you. Don’t wait for a catastrophe to reclaim your autonomy. Stand your ground, document everything, and never prioritize someone else’s ego over your own security.
What about you? Have you ever had to draw a firm line in the sand when it came to a partner’s financial recklessness, or have you been on the receiving end of a wake-up call? Let’s discuss in the comments below—is it ever possible to rebuild trust after such a profound betrayal, or is the damage always permanent?
What's your verdict on this dilemma?
Vote below to contribute to the official community consensus.
Have a Dilemma Keeping You Up at Night?
Share your real-life feud, wedding chaos, or relationship crossroads anonymously with our editorial team.
What do you think ?
0 Comments🛡️ Comments are moderated to protect community integrity. Your comment will appear once approved by the editorial team.